

Bicycle Coverage in Home Insurance—A Useful Add-On or Superfluous?
19. January 2026
Why Traffic Legal Protection Insurance Is So Important
10. February 2026Bicycle Coverage in Home Insurance—A Useful Add-On or Superfluous?
19. January 2026Why Traffic Legal Protection Insurance Is So Important
10. February 2026Coverage for Uncollectible Debts in Personal Liability Insurance
Bad debt coverage is one of the most important—and at the same time most frequently underestimated—components of personal liability insurance. Anyone who specifically searches for “bad debt coverage” or “bad debt coverage for personal liability” usually has a specific concern:
What happens if someone causes me harm but can't pay?
It is precisely this risk that is often underestimated, with costly consequences.
The Benefits of Bad Debt Coverage at a Glance
- Coverage for Uninsured Third Parties: Your insurance will pay if the person responsible does not have liability insurance.
- Protection in the Event of Insolvency: You are protected even if the party responsible for the damage is insolvent or lacks assets.
- Compensation for personal injury and property damage, such as medical expenses, compensation for pain and suffering, lost wages, or damaged property.
- Financial security even when liability is clear: You won't be left to foot the bill just because the person responsible can't pay.
- Low additional premium—great value, plenty of coverage for just a few euros a year.
What does "bad debt coverage" mean in personal liability insurance?
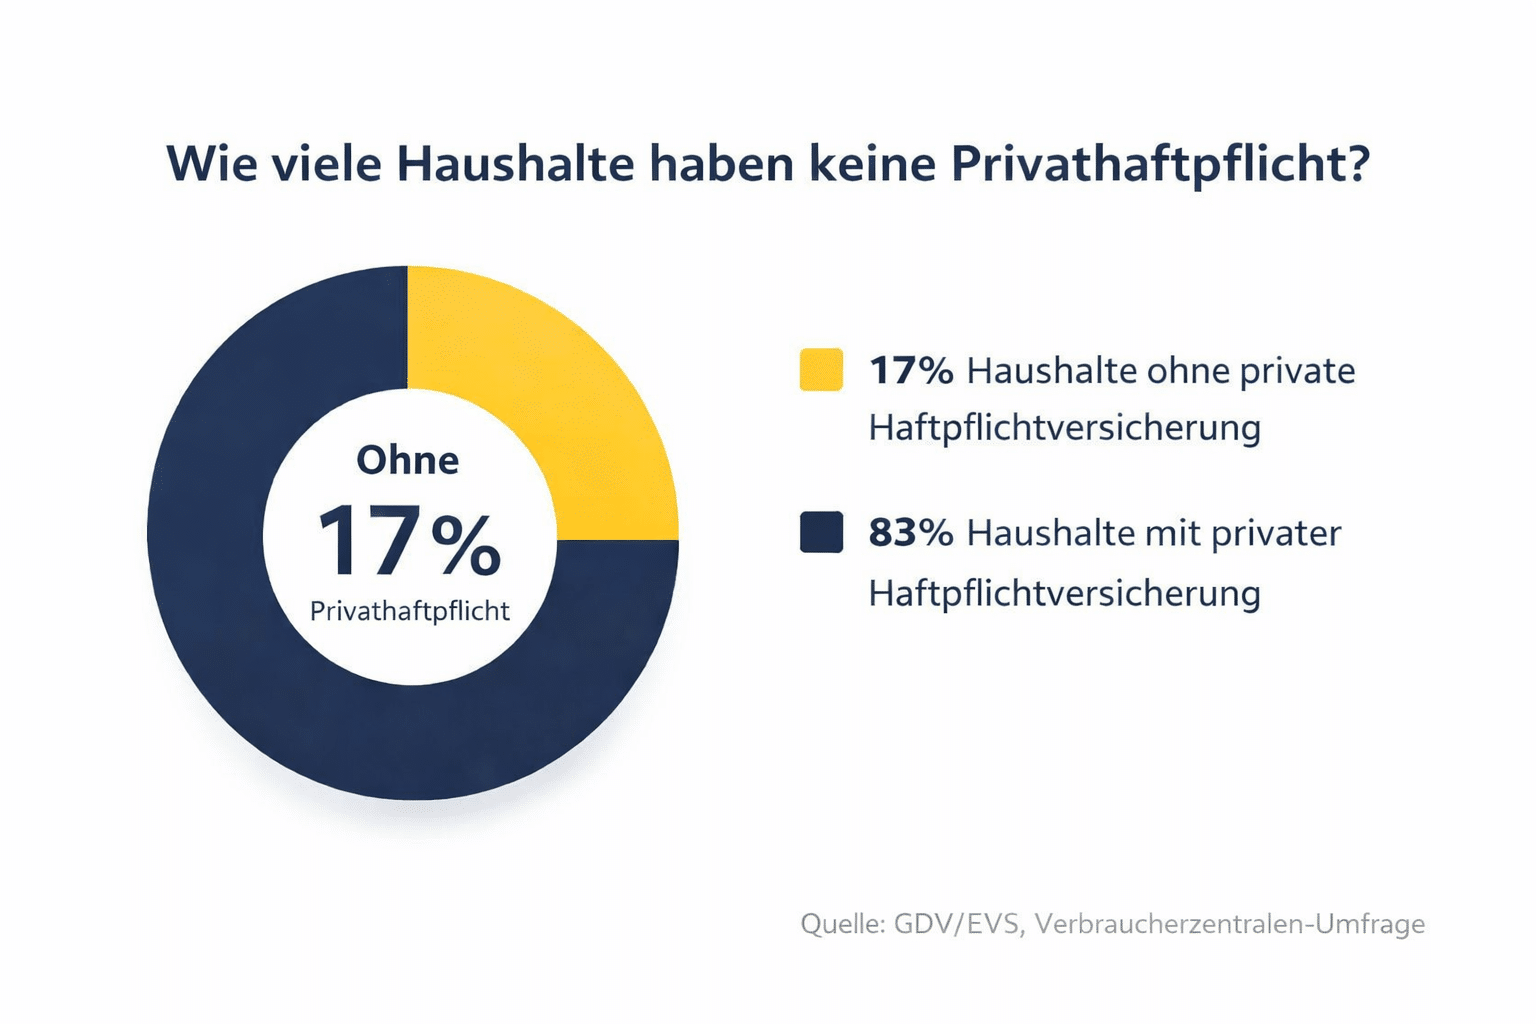
Bad debt coverage under personal liability insurance applies when a third party causes you damage and:
- the claim for damages is legally valid
- the person responsible does not have personal liability insurance, or
- the party responsible is insolvent (e.g., personal bankruptcy)
In this case, your personal liability insurance will cover the damages.
Without bad debt coverage, the injured party is often left to bear the costs, even when liability is clear.
A real-life example: When the damage is clear—but no one will pay
A typical example from everyday life:
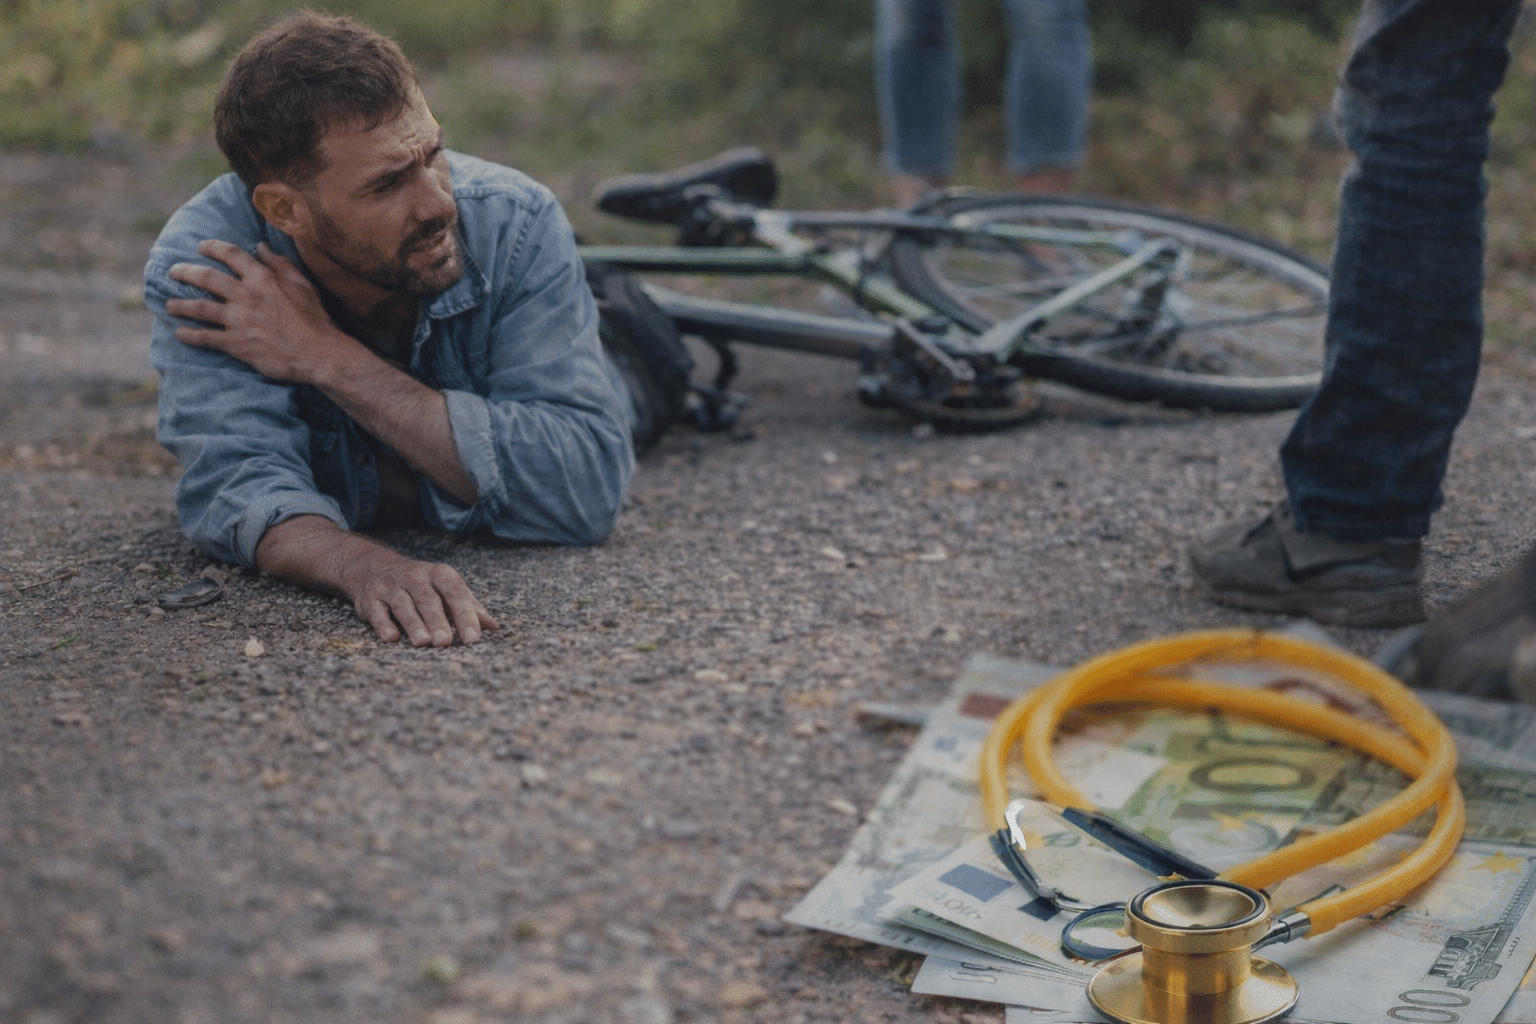
You are walking when you are struck by a cyclist. The question of fault is clear. You sustain injuries, require medical treatment, and are unable to work for several weeks.
The party responsible for the damage: does not have personal liability insurance, has no assets subject to seizure, and cannot compensate for the damage
Without bad debt coverage, this means for you: no compensation for pain and suffering, no compensation for lost wages, and no reimbursement of medical expenses
If your personal liability insurance includes coverage for bad debts, your insurance company will cover these costs.
What types of losses does 's bad debt coverage cover?
Depending on the terms of the insurance policy, bad debt coverage includes:
- Personal injury (e.g., medical expenses, compensation for pain and suffering, loss of earnings)
- Property damage (e.g., smartphone, bicycle, glasses)
- Consequential Financial Losses
Important: Many insurers will only pay out once the damages reach a certain minimum amount and require proof that the party at fault is insolvent.
Why Many Personal Liability Insurance Policies Have Shortcomings in This Area
Many policyholders assume that their personal liability insurance automatically includes coverage for bad debts. In practice, however, it often turns out that:
- Older rate plans do not include bad debt coverage
- High minimum coverage limits restrict benefits
- Terms and conditions are complicated or outdated
Particularly in the case of long-term contracts, the coverage for bad debts under personal liability insurance is often no longer in line with current standards.
For whom is bad debt coverage particularly important?
Bad debt coverage makes sense for almost everyone, but especially for:
- Working Individuals (Insurance Against Loss of Earnings)
- Families with children
- Pedestrians and cyclists
- People without substantial financial reserves
After all, you can’t control who causes you harm—but you can ensure that you’re financially protected in case of an emergency.
Conclusion: Coverage for bad debts is a must in personal liability insurance
Debt default coverage under personal liability insurance does not protect you from your own mistakes, but rather from the financial consequences of others’ mistakes.
The additional premium is small—but the risk of going without this coverage could threaten your livelihood.
Check Your Personal Liability Insurance Now
Would you like to know if your personal liability insurance includes comprehensive coverage for bad debts?
We'll check the following for you:
- whether bad debt coverage is in place
- at what loss threshold it takes effect
- whether your plan is still up to date
The exam is free, non-binding, and explained in a way that's easy to understand.
Check your personal liability coverage now and get the best protection.