

Basic Disability Insurance for Deutsche Bahn Employees with a Shortened Medical Questionnaire
19. March 2026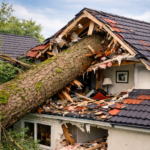
A neighbor’s tree falls on my house—who pays for the damage?
30. March 2026
Does home insurance cover a bicycle stolen from the basement?
Your bike is gone—even though you parked it safely in the basement. Here, we explain in simple terms when your home insurance will cover the loss, what you need to watch out for, and what pitfalls to avoid.
General Rule: Bicycles are covered under household property insurance
It’s a huge shock: The bike is gone—even though it was parked safely in your own basement. At that moment, many people ask themselves: Does my home insurance even cover a bike stolen from the basement?
However, whether the insurance company actually pays out—and how much—depends on several factors: the plan you chose, the specific circumstances of the theft, and how well the bike was secured. The following sections explain what matters.
When does insurance pay out for theft from the basement?
In order for home insurance to cover the theft of a bicycle from the basement, three conditions must generally be met:
1. There must be a burglary
Home contents insurance generally only pays out in the event of what is known as a “burglary.” This means that the perpetrator must have gained entry by force—for example, by breaking open a basement door or prying open a lock. A basement that is simply left open or unlocked is not sufficient to trigger insurance coverage.
2. The bicycle was properly secured
Many insurers require that the bicycle be secured in the basement—for example, with a bike lock or chained to a fixed object. If this security measure is missing, coverage may be reduced or denied entirely. What counts as “adequate security” varies depending on the policy—reputable providers define this in a practical and transparent manner.
3. The basement is part of the insured apartment
The basement room must be part of the insured apartment. Shared basements in apartment buildings are often covered under the policy—however, stricter requirements often apply regarding proof of the burglary and securing the bicycle.
Special Case: Theft Without Breaking and Entering
What happens if the bicycle was stolen from an unlocked basement or an open common area? In this case, it is not considered burglary—and homeowners insurance generally does not cover the loss.
This also applies if the bicycle was secured with a lock: What matters is whether the perpetrator forced his way into the room—not just whether he broke the lock on the bicycle itself.
The Bicycle Clause: When It Matters
Many home insurance policies include an optional “bicycle clause.” This clause extends coverage beyond just break-ins into the basement:
- Protection even in case of theft outdoors—for example, outside a supermarket or at a train station
- 24/7 coverage, including at night depending on the plan
- Reimbursement up to a contractually agreed-upon amount
- Particularly useful for high-quality bikes, e-bikes, or cargo bikes
For theft from your own basement, the bicycle clause is often not strictly necessary—this scenario is already covered by burglary protection in many insurance plans. However, if you want to insure your bicycle outside your home as well, you’ll need this clause.
Common Pitfalls — and How Good Plans Can Help
In practice, claims settlement often runs into trouble at the same points. Here are the most common problems—and how high-performance plans handle them:
- Keller was not conclusive: Good terms and conditions are more customer-friendly in their wording and, in some cases, avoid overly strict language.
- No clear evidence of a break-in: Comprehensive insurance plans offer extended theft coverage or more lenient terms in cases where the evidence is unclear.
- The bicycle was not secured with additional measures: Reputable insurers define security requirements in a practical way—based on what is actually feasible in everyday life.
- Insufficient coverage: Premium plans offer higher coverage limits that also cover modern e-bikes and expensive road bikes.
- Unclear regulations regarding communal basements: Transparent insurers have clear terms and conditions—even for apartment buildings.
What to Do in the Event of a Claim?
If your bike has been stolen from the basement, it’s important to act quickly and in an organized manner. The following three steps are crucial:
- Notify the police and file a report: The police report is the most important basis for insurance claims settlement. Without a report, almost no insurer will pay out.
- Document the damage: Take photos of the broken-into basement, the damaged lock, and anything else that indicates a break-in. Also, have your proof of purchase and the frame number ready.
- Report an insurance claim—as soon as possible: Many policies have short reporting deadlines. Don’t wait too long, or you risk having your claim denied due to late reporting.
Rate Comparison: High-Performance vs. Low-Performance
Not all home insurance policies offer the same level of coverage for bicycle theft. The differences are significant when you look at the details:
| Criterion | High-Performance Plan | Weak plan |
|---|---|---|
| Definition of Burglary | Broader definition — covers more cases | Very narrow — many cases fall through the cracks |
| Safety Requirements | Realistic, practical requirements | Strict regulations, often grounds for rejection |
| Bicycle Compensation | High coverage limits or flexibly expandable | Low limits (e.g., 1–2% of the insured amount) |
| Communal Basement | In practice, these are usually covered by insurance | Often limited or excluded |
| Bicycle Clause | A Sensible Addition Is Possible | Few options available or expensive to retrofit |
| Claims Settlement | Customer-Focused & Accommodating | Bureaucratic — quick rejection possible |
Conclusion: Good opportunities—but pay attention to the terms and conditions
In many cases, home insurance covers the theft of a bicycle from the basement—provided it was stolen during a break-in and the bicycle was properly secured. If you know and follow these basic rules, you’ll be on the safe side in the event of an emergency.
Problems almost always arise when the policy coverage is insufficient, documentation is missing, or the insurance company was notified too late. With a comprehensive policy and the right steps taken in the event of a claim, you’ll be well protected—even for expensive bikes.
Check your current policy: Are bicycles adequately covered? What is the compensation limit? Is there a bicycle clause? If you can’t answer these questions, you should consult with an independent insurance broker.
Is your bike adequately insured?
We’ll review your current home insurance policy for free and let you know if there’s room for improvement—so you won’t face any unpleasant surprises in the event of a claim.